Legacy Title Company Blog
Why the Best Closings are Often the Least Eventful
Why the Best Closings are Often the Least Eventful
The best closings are often the least eventful.
No last-minute surprises. No frantic phone calls. No unexpected hurdles on closing day. Just a real estate transaction that progresses smoothly from contract to closing.
From a buyer's or seller's perspective, it can seem effortless. But effortlessness does not mean effort-free. A closing is more than a moment; it is an experience built across the entire transaction.
What people remember about closing is not usually the paperwork. It is whether they felt informed, prepared, and confident throughout the process. Those impressions are often formed long before closing day, through the preparation, coordination, and communication that happen along the way.
A Smooth Closing Starts Before Closing Day
At Old Republic Title, the closing experience begins long before the documents are signed. It is the cumulative experience of knowing what is happening, what comes next, and who is helping move the transaction forward.
Consider two transactions with similar circumstances, but very different closing experiences.
In the first, everyone feels like they are reacting. Questions linger, deadlines feel uncertain, and issues are addressed only after they create delays.
In the second, everyone feels prepared. Expectations are clear, communication is consistent, and potential concerns have been identified and addressed early.
The difference isn't luck. It's the result of intentional work by professionals to help make the process more predictable and less stressful.
Confidence Comes From Knowing What Happens Next
Confidence doesn’t happen by accident. It’s built through the small moments that show progress is being made, from timely updates and courtesy check-ins to knowing what comes next and when to expect it.
Much of that confidence is built behind the scenes. From the moment a transaction begins, title professionals help coordinate the people, information, and details that keep the process moving forward.
- Research ownership history
- Identify potential title concerns
- Help safeguard property ownership rights
- Coordinate details and manage timelines
Most of this work goes unnoticed, and that is usually a good thing. Great service often works quietly in the background, reducing uncertainty, providing clarity, and creating greater peace of mind.
Coordination Turns Complexity Into Progress
For many buyers and sellers, uncertainty is one of the most challenging aspects of a real estate transaction.
A transaction can be moving forward exactly as it should, but without clear communication, it may not feel that way. When people do not know what is happening or what comes next, uncertainty quickly fills the gaps.
- Are we still on schedule?
- What is happening next?
- Are we waiting on something?
- Is there a problem nobody has told me about?
Communication helps answer those questions by providing visibility into the process, reinforcing expectations, and keeping everyone aligned.
When expectations, timelines, and responsibilities remain clear, complex transactions become easier to navigate.
An uneventful closing is not one where nothing happens. It is one where the right things happen at the right time. That is how coordination turns complexity into progress.
Let the Milestone be the Memorable Part
Buyers and sellers may not remember every document they signed, but they will remember the relief of reaching closing day. They will also remember how the process felt and who helped get them there.
For more than a century, Old Republic Title has helped customers and clients move through important milestones with clarity, confidence, and trusted support. That experience has reinforced a simple belief: a successful closing is about more than reaching the finish line.
In the end, that’s what makes the best closings the least eventful ones.
Senior Housing Boom
The Senior Housing Boom: A New Era of Growth
June 17, 2026
Occupancy in the senior housing sector is surging toward its highest level in nearly twenty years, according to the National Investment Center for Housing & Care (NIC). The absorption rate (the number of units that are newly occupied compared to how many are available) is outperforming every historical benchmark, and the market is pricing senior housing properties above peak levels seen in previous real estate cycles. For commercial real estate (CRE) investors, developers, and brokers, this isn't a moment in time—it may be the beginning of a generational transformation of the asset class.
So, what’s powering the surge? Let’s unpack the demographic wave reshaping demand, the tightening supply pipeline, and the new development realities redefining the sector.
The Demographic Wave
The U.S. is entering the steepest aging curve in modern history, which is expected to reshape the senior housing sector for decades. The over-65 population has already reached 59 million, representing 18% of the nation’s population, and is expected to climb to roughly 78 million by 2040. The oldest Baby Boomers also turn 80 this year, marking the beginning of a steady rise in demand for senior housing across all care levels.
There has also been a major shift in how Americans age and it is redefining living and support needs. Smaller families, fewer available caregivers, and changing economic and social conditions are pushing older adults away from traditional aging-in-place models. According to research conducted by the PwC and the Urban Institute, the number of adults over 75 living alone is expected to more than double by 2040, and adults 65–74 are now the fastest growing age group of renters. Meanwhile, equity-rich Baby Boomers make up 42% of all homebuyers1, according to the National Association of REALTORS® 2026 Home Buyers and Sellers Generational Trends Report. These factors give this demographic the financial power and motivation to transition into purpose-built senior housing as they age.
Supply Pipeline
Senior housing construction starts and units that are under development are at their lowest levels since 2012–2014, affecting every major asset class:
- Independent Living
- Assisted Living
- Memory Care
- Continuing Care Retirement Communities
- Active Adult (55+) communities
Over the last four quarters, only 7,1002 new senior housing units broke ground, a level comparable to 2009 during the housing crisis. According to Cushman & Wakefield’s U.S. Senior Living & Care Investor Survey and Trends Report, net absorption outpaced supply demand 4.8 to 1 in 2025, as the number of units under construction fell to 2.3%, the lowest level since 2012. JLL’s 2026 Seniors Housing and Care Investor Survey and Trends Outlook (JLL Senior Survey) reports that new construction starts declined 77%3 in primary markets and 60%3 in secondary markets, and have been consistently below the past 10-year average.
Investment Momentum
With demand for senior housing accelerating and new development constrained by a slow-moving supply pipeline, investors are increasingly recognizing the sector’s long-term benefits. According to the JLL Senior Survey, 86%3 of surveyed investors indicated plans to expand their exposure, underscoring growing institutional confidence in the asset class. Operational performance continues to strengthen, with occupancy climbing to 89.5%4 in Q1 2026, the twentieth consecutive quarter of increasing occupancy rates, according to the NIC. At the same time, the number of units being built has slipped to its weakest level since 2012, while inventory expanded by just 0.4%4 year-over-year in Q1 2026—a historic low. Per-unit pricing has increased by more than 40% year-over-year5, while cap rates, which measure the income yield, have compressed to around 6.2% on average6 and are widely expected to further decline. These trends show that senior housing is emerging as a stabilized, income-generating sector.
Debt markets are supporting senior housing by stabilizing floating-rate loans, providing essential liquidity for acquisitions, and enabling operators to expand and renovate. For instance, the U.S. Department of Housing and Urban Development (HUD)’s Section 232 program recorded roughly $5.96 billion to $6 billion in closed loans across 337 transactions in fiscal year 2025. The Federal Housing Finance Agency expanded liquidity by raising Fannie Mae and Freddie Mac’s combined multifamily lending caps to $176 billion for 20267, a 20.5% increase that adds roughly $30 billion of additional lending capacity to the market. These shifts indicate that lenders and government agencies are all re-engaging and directly supporting the rise in transaction velocity across the senior housing sector.
Also shaping the current landscape is a growing investor preference to acquire existing properties to renovate, rather than pursue new development. This shift is driven by ongoing supply constraints, as well as the increasing financial and operational challenges associated with ground-up projects. Elevated construction costs, expensive materials, and tighter capital markets have pushed new development to its lowest level since 2012, with projections calling for a shortfall of up to 550,000 units by 2030, representing a $275 billion investment shortage.8 Inventory growth has slowed to between 0.4% and 0.7% annually, far below what is needed to meet demand, making existing assets increasingly scarce and highly sought after.
Outlook
The senior housing sector has shifted to one of the hottest commercial real estate sectors, driven by demographic demand, historic construction slowdown, and tightening occupancy. For CRE investors, developers, and brokers, this supply-demand imbalance translates to momentum that is not expected to slow down any time soon. This shift may translate into a steady pipeline of transaction opportunities with long-term upside.
At Old Republic Title, we understand the importance of certainty, speed, and precision at every stage of a senior housing transaction. Our team of highly experienced attorneys, underwriters, closers, and title specialists assist in delivering customized title and closing services to clients across the nation. To learn more and find a representative near you, visit oldrepublictitle.com/locations.
1 Copyright ©2026 “Home Buyers and Sellers Generational Trends Report 2026.” NATIONAL ASSOCIATION OF REALTORS®. All rights reserved. Reprinted with permission. April 15, 2026. https://www.nar.realtor/research-and-statistics/research-reports/home-buyer-and-seller-generational-trends
2 “Senior Housing Demand Outpaces New Supply in 3Q24.” October 3, 2024. National Investment Center for Seniors Housing & Care. https://www.nic.org/news-press/senior-housing-demand-outpaces-new-supple-in-3q24/
3 Copyright ©2026 “Seniors Housing and Care Investor Survey and Trends Outlook Spring 2026.” Jones Lang LaSalle IP, Inc. (JLL). All rights reserved. Linked with permission. Spring 2026. https://www.jll.com/content/dam/jllcom/en/us/documents/reports/research-reports/26-insights-seniors-housing-care-investor-survey-and-trends.pdf?utm
4 “Senior Living Occupancy Grows Amid Construction Slowdown, Limiting Options for Older Adults.” April 23, 2026. National Investment Center for Seniors Housing & Care. https://www.nic.org/news-press/senior-living-occupancy-grows-amid-construction-slowdown-limiting-options-for-older-adults/
5 “Senior Housing: 5 Key Trends to Watch in 2026.” NIC MAP. December 1, 2025. Updated April 16, 2016. https://www.nicmap.com/blog/senior-housing-five-key-trends-to-watch-in-2026/
6 “Senior Housing as an Alternative Asset Class: A Data-First View.” June 3, 2026. National Investment Center for Seniors Housing & Care. https://www.nic.org/nic-academy/alternative-asset-class/
7 “Fannie, Freddie Multifamily Loan Purchase Caps to Rise 20% in 2026.” National Association of Homebuilders, November 25, 2025. https://www.nahb.org/blog/2025/11/fannie-freddie-multifamily-loan-purchases
8 “Go long in senior housing: NIC MAP Vision data reveals a $275 billion investment shortage in senior housing developments across the country by 2030.” NIC MAP. June 26, 2024. https://www.nicmap.com/news/go-long-in-senior-housing-nic-map-vision-data-reveals-a-275-billion-investment-shortage-in-senior-housing-developments-across-the-country-by-2030/
Old Republic Title, its officers and employees do not provide, and this communication is not intended to be, investment, tax or legal advice. Old Republic Title makes no representations or warranties regarding the accuracy of the information or tax consequences addressed herein. You should consult an investment, tax or legal professional of your choosing to advise you of the benefits and risks of your specific transaction.
Top Five CRE Markets to Watch in 2026
Top Five CRE Markets to Watch in 2026
January 21, 2026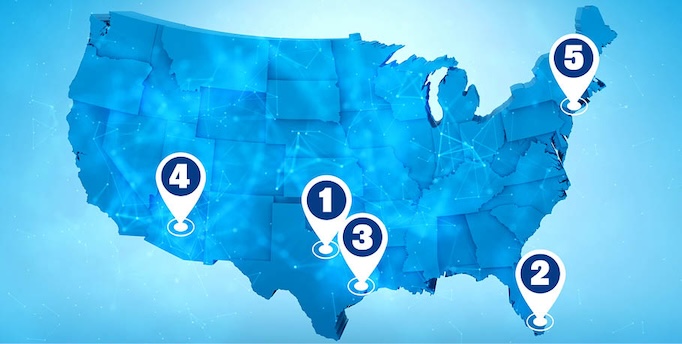
2026 is projected to be a landmark year for commercial real estate (CRE). Investors aren’t just looking for growth—they’re chasing markets with unstoppable momentum, economic resilience and unbeatable returns. Ready to see where the next wave of opportunity is expected? Let’s explore the cities driving growth today and positioned to lead in 2026.
1. Dallas–Fort Worth Metroplex, Texas
Consistently ranked as a top destination for CRE investment by various major brokerage, analytic and investment firms, the Dallas-Fort Worth metroplex (DFW metroplex) is experiencing explosive growth with no signs of slowing down. Investors, developers, lenders and corporate business operations continue to be drawn to this land-rich area. Developers are buying up land at a breakneck pace to bring new subdivisions with affordable housing, shopping centers, industrial warehouses, healthcare facilities, restaurants and more – all to meet the demands of the growth. Here are some of the key drivers behind the DFW metroplex sustained popularity:
• Retailtainment: The retail market is transitioning into a “retailtainment1” hub as mixed-use projects blend shopping, dining and entertainment to boost consumer engagement. Over 7.1 million square feet (msf) of new retail construction is underway2, much of it anchored by experiential concepts like pickleball venues, rooftop dining and lifestyle hubs.
• Corporate relocations and expansions: The DFW metroplex leads in corporate relocations. It attracted 100 new corporate headquarters from 2018 to 20243—and this momentum shows no signs of slowing down in 2026. Click here to see which companies moved to the DFW metroplex during 2023 and 2024; and for a map of relocations as of 2025, click here.
• Data center expansion: The DFW metroplex is rapidly emerging as a major hub for artificial intelligence (AI) data centers, with multiple projects underway and strong funding prospects in 2026. A prime example is global technology leader Wistron, which is investing $761 million into the establishment of its first U.S. manufacturing site focused on producing AI supercomputers and related components.4
2. Miami, Florida
Miami remains a premier Sun Belt market, supported by economic strength and dynamic growth trends that consistently rank the city among the top choices for CRE investment firms. Key catalysts include the region’s rise as “Wall Street South,” driven by the migration of financial firms and high-net-worth individuals. Some other significant catalysts include:
• Foreign investment: Miami’s world-class airport and seaport infrastructure make it a hub for logistics and international business. According to the 2025 Miami New Construction Global Sales Report compiled by the MIAMI Association of REALTORS®, 73 countries have purchased new construction units over the last 22 months5, including pre-construction and condo conversion sales.
• Luxury appeal: Miami has become one of the world's top luxury real estate destinations for its beachfront condos that feature resort-style amenities and waterfront estates with private docks.
• Favorable tax and business policies: Florida offers a highly favorable tax environment for investors. The state imposes no personal income tax, which means higher net returns for investors. In Miami, both the city and county also maintain no property tax on business inventories and no corporate tax on limited partnerships.
3. Houston, Texas
Houston delivers a rare combination of expansive land, long-term growth potential and lower entry costs compared to other major markets. Some of the top factors contributing to Houston’s CRE surge include:
• Global shipping hub: Port Houston is a critical gateway for global trade along Texas’ 367-mile Gulf Coast, one of the most active trade corridors in the U.S. In 2024, total trade through the port surged to $223.5 billion—a remarkable 42% increase since 2019.6 As a net exporter by trade value, Port Houston recorded $129.9 billion in exports compared to $93.7 billion in imports5, reinforcing its role as a powerhouse for outbound U.S. goods.
• Energy: Texas dominates U.S. energy production—leading in oil, gas, wind and solar—and generates nearly one-fourth of all domestic energy. As the number two liquified natural gas (LNG) exporter and a top producer of hydrogen, carbon capture, battery storage and modular nuclear power, Texas is driving the future of energy innovation.7
According to information compiled by the Greater Houston Partnership, Houston is home to over 4,200 energy-related firms and major global headquarters8, creating a strong demand for industrial, logistics, and specialized facilities and prime opportunities for CRE investors.
4. Phoenix, Arizona
Its proximity to major West Coast markets, combined with comparatively lower operating costs and plentiful land for development, positions Phoenix as a high-potential destination for CRE investment. Major drivers in the area include:
• Industrial/Manufacturing: The Phoenix industrial market posted an impressive Q4 2025, which is expected to continue in 2026. Taiwan Semiconductor Manufacturing Company (TSMC) has significantly expanded its footprint in North Phoenix, acquiring approximately 900 additional acres for $197.25 million on January 7, 2026.9 This purchase builds on the 1,129 acres purchased in 2020, bringing TSMC’s total land holdings in the area to more than 2,000 acres for its major semiconductor campus expansion.
• Healthcare: Phoenix is experiencing a healthcare CRE surge due to rapid population growth, aging demographics, and the industry’s goal to increase both medical office buildings (MOBs) and conduct major hospital expansions. Mayo Clinic announced in early 2025 that it is making a $1.9 billion investment to transform its Phoenix campus with a 1.2 million-square-foot expansion that will increase clinical space by nearly 60%.10
5. Brooklyn & Manhattan, New York City
Manhattan continues to be a global mecca with concentrations in finance, law and media, while Brooklyn has become a centralized location for tech, creative agencies and startups, making both boroughs highly attractive to CRE investors. Some recent highlights for each borough include:
• Class A and trophy office buildings in Manhattan: There has been a surge in the construction and leasing of Class A and “trophy” office buildings, mostly due to a demand from tech and financial firms for premium spaces with cutting-edge amenities. According to Cushman & Wakefield’s Q3 Manhattan’s Office MarketBeat, there was 7.3 msf11 of new leasing activity, which marked the third straight quarter of elevated activity. Year-to-date volume reached 23 msf, up 37.6% from 202411, positioning 2025 as one of Manhattan’s strongest leasing years since 2019.
• Overall pricing indicators in Brooklyn: Record-high price-per-square-foot metrics, rapid investment sales, strong demand for development sites and rising rents – all fueled by limited supply and shifting demands – is placing Brooklyn at the CRE forefront.
• Affordable housing initiatives: CRE professionals are watching as New York seeks to advance housing stability by tightening rent stabilization and improving enforcement, while advancing initiatives like the Tenant Opportunity to Purchase Act (TOPA) and Community Opportunity to Purchase Act (COPA). TOPA would give tenants a chance to purchase their buildings, and COPA would offer nonprofits and community land trusts first rights on Multifamily sales—both aimed at preserving affordability and community control amid ongoing legislative debate.
Beyond the top five, there are additional markets that continue to attract attention from CRE investors and developers. These cities also have promising opportunities worth watching:
- Austin, Texas
- Raleigh-Durham, North Carolina
- Nashville, Tennessee
- Tampa-St. Petersburg, Florida
- Northern New Jersey and Jersey City
Old Republic Title’s CRE Footprint
As CRE markets continue to evolve, investors, developers, lenders, corporate firms – and the brokers and attorneys who guide them – need title and closing solutions that deliver expertise, efficiency, accuracy and timely service. That’s where Old Republic Title comes in. Our top-tier products and services are curated to safeguard your investment and provide the clarity you need to close with confidence. From clearing complex title issues and complying with state and federal laws, to managing multistate and multisite projects, we deliver the skill, reliability and financial strength that commercial transactions demand.
Old Republic Title maintains a strong presence not only in the top five CRE cities, but throughout cities nationwide. Our National Commercial Services (NCS) team – comprised of highly experienced attorneys, underwriters, closers and other title specialists – combine local market insight with national resources to deliver customized solutions and underwriting strategies.
Ready to put our expertise to work for your next transaction? Visit oldrepublictitle.com/ncs to connect with a dedicated representative and discover how our tailored title and escrow solutions can help you close with confidence.
Old Republic Title, its officers and employees do not provide, and this communication is not intended to be, investment, tax or legal advice. Old Republic Title makes no representations or warranties regarding the accuracy of the information or tax consequences addressed herein. You should consult an investment, tax or legal professional of your choosing to advise you of the benefits and risks of your specific transaction.
Sources:
1 CrispIdea. Retailtainment: Merging Shopping with Entertainment. May 20, 2025. https://www.crispidea.com/retailtainment-shopping-experiences/?srsltid=AfmBOoqthjGbPqFCDLpziG9vg4bTI8JAZgK4dakH95pFGFfpl5pJLJ__
2 CultureMap Dallas. Dallas comes in at No. 1 in the U.S. for retail construction in 2025. July 25, 2025. https://dallas.culturemap.com/news/innovation/dfw-retail-construction-2025/
3 CultureMap Dallas. Dallas ranks No. 1 city in U.S. for corporate HQ relocations. June 20, 2025. https://dallas.culturemap.com/news/innovation/corporate-headquarters-relocations-dfw/
4 Fort Worth Inc. Wistron Picks Fort Worth for First U.S. Manufacturing Site, a $761M AI Investment. August 21, 2025. https://fortworthinc.com/news/wistron%E2%80%99s-first-u-s-plant-lands-in-fort-worth-in-761m-ai-fac/
5 Miami and MIAMI REALTORS®. New International Report: Global Buyer Share Increases for Miami New Construction Units; Buyers from 73 Countries. November 11, 2025. https://www.miamirealtors.com/2025/11/11/new-international-report-global-buyer-share-increases-for-miami-new-construction-units-buyers-from-73-countries/
6 Texas Comptroller. Port of Entry: Houston Impact to the Texas Economy, 2024. https://comptroller.texas.gov/economy/economic-data/ports/2024/houston.php
7 Texas Economic Development & Tourism Office. Energy Evolution https://gov.texas.gov/business/page/texas_energy#:~:text=Texas%20powers%20America's%20economy.&text=Texas%20leads%20the%20nation%20in,Renewables
8 Greater Houston Partnership. Houston: Welcome to the Energy Capital of the Word. https://houston.org/why-houston/industries/energy/
9 AZ Big Media. TSMC buys 900 acres of land in North Phoenix for $197 million. January 8, 2026. https://azbigmedia.com/real-estate/tsmc-buys-900-acres-of-land-in-north-phoenix-for-197-million/
10 City of Phoenix. Mayo Clinic Announces $1.9B Investment in Phoenix. March 3, 2025. https://www.phoenix.gov/newsroom/ced-news/3373.html
11 Manhattan Office Market Maintains Strong Momentum with Robust Class A Leasing in Q3 2025, According to Cushman & Wakefield. October 10, 2025, https://www.cushmanwakefield.com/en/united-states/news/2025/10/manhattan-office-market-maintains-strong-momentum-with-robust-class-a-leasing
Date Center Real Estate: Important Decisions
Data Center Real Estate: Important Considerations
October 30, 2025
While industrial warehouses have expanded rapidly to meet the demands of the ever-growing e-commerce economy, another type of “warehousing” is quietly reshaping the commercial real estate (CRE) landscape: data centers. These facilities—dedicated to housing servers, storage systems and networking equipment—are the backbone of our digital world.
As the CRE industry evolves, data centers are emerging as a cornerstone of global infrastructure, fueling a multi-billion-dollar market. But with their growth comes complexity. In this blog, we’ll explore the demand for data centers, discuss key considerations and challenges they present to developers and investors, and highlight significant title insurance factors to consider.
The Current Landscape
Although data centers can be traced back to the mid-1900s, the demand for data storage has skyrocketed in recent years, due to our growing reliance on cloud-based data solutions and everyday use of artificial intelligence (AI). In particular, there has been substantial construction of colocation centers (data centers leased to a third-party tenant) and hyperscale data centers (massive facilities engineered for large-scale workloads with an optimized network infrastructure, streamlined network connectivity and minimized latency.)
Colocation centers are in high demand with vacancy rates dropping to historically low rates. This tight supply is expected to persist through 2027, as nearly three-quarters of new capacity is already preleased. The colocation sector is estimated to grow approximately 20% through 2030, potentially reaching 42 gigawatts of capacity.
Meanwhile, hyperscale data centers are growing rapidly alongside development, expanding to secondary and tertiary markets to reduce latency and avoid power constraints. One industry source estimates that up to $1 trillion in new data center development will be required in North America alone by 2030 to meet demand.
As of October 2025, the U.S. data center market is one of the most dynamic and rapidly expanding sectors in commercial real estate. With industry sources estimating more than 5,400 active data centers nationwide, the sector continues to attract significant investment and development. The states presently hosting the highest number of data centers include Virginia, Texas, California and Ohio, each offering distinct advantages in projects from small regional centers to hyperscale environments.
Key Considerations
There are several key factors that developers and investors should consider before initiating a data center project. These include:
• Location. When selecting data center locations, key factors include physical accessibility, property values, labor costs, and climate risks like floods, earthquakes, or wildfires, which may require extra engineering and insurance measures. Cooler climates can maintain temperature regulation expenses.
Access to scalable, affordable, and reliable energy is essential due to high electricity demands. Proximity to fiber optic infrastructure and internet exchange points ensures strong network connectivity. Being near major markets reduces latency, which is especially critical for last-mile data centers delivering digital services to end users.
• Infrastructure. The cost of constructing a data center is substantial, given their intense power, data communication and equipment needs, not to mention the physical space that is necessary. A data center will also require a sophisticated cooling system to offset the heat generated by operating equipment, ensuring that temperatures support optimal performance of computing infrastructure. That said, it is not unusual for construction costs to fall in the hundreds of millions of dollars, with as-built values often exceeding $1 billion.
• Tax incentives. Some states offer tax incentives, such as sales and use tax exemptions on equipment and electricity, for the construction and operation of data centers built within certain parameters. Certain local jurisdictions have regulations that are more friendly to data center development.
At the federal level, the One Big Beautiful Bill Act (OBBBA) introduces a range of tax incentives aimed at encouraging strategic infrastructure investments, including investments in data centers:
- 100% Bonus Depreciation (through 2029): Data centers can deduct the full cost of qualified capital equipment and property in the year it's placed in service, rather than depreciating it over time. This significantly improves cash flow and accelerates cost recovery.
- Section 179D Energy-Efficient Building Deduction (until June 30, 2026): Allows deductions for energy-efficient systems like HVAC, insulation, and lighting—critical for data centers due to their high energy demands.
- Expanded Opportunity Zones: The OBBBA renews and enhances Opportunity Zone programs, including a new Qualified Rural Opportunity Fund offering a 30% basis increase for investments held at least five years. This can benefit data centers located in designated zones.
• Title insurance underwriting requirements. Title insurers face a uniquely complex set of risks when underwriting data center projects, particularly due to the high construction values and substantial loan amounts involved. One of the most significant concerns is managing mechanics lien exposure, especially in colocation centers where large-scale tenants often conduct their own buildouts or install specialized equipment. These tenants typically work with independent vendors and enter into lease agreements that restrict the landlord from disclosing details about tenant improvements. This lack of transparency can create a blind spot for title insurers if they do not remain aware of ongoing construction that could result in lien claims.
In jurisdictions that apply the relation-back doctrine, mechanics liens recorded during construction can take priority over previously recorded mortgages, potentially jeopardizing the insured lender’s position if the insurer was unaware of the work. Beyond lien risks, title insurers must also navigate challenges such as subdividing large parcels, ensuring accurate legal descriptions, and verifying utility easements, rights-of-way and other matters related to reliable utility access, which is essential for data centers due to their high power and connectivity demands.
Given the scale and complexity of these transactions, many are coinsured, with multiple title insurance underwriters sharing the risk. Working with an experienced commercial title underwriter is vital to navigate the nuanced title issues that often arise. As data centers continue to grow in strategic importance, the ability to understand and mitigate these risks becomes increasingly critical for the title insurance industry.
Challenges
Developers and investors should also be aware of potential challenges associated with data centers.
• Power outages. Because data centers demand very high levels of energy, they can tax older power grids, leading to outages and increased prices for customers.
• Noise pollution. Noise levels emanating from a data center can be substantial depending on the equipment being housed.
• Sustainability. With increasing international interest on the subject of sustainability, there are initiatives in the CRE arena for data center projects to responsibly adopt technologies that help reduce water consumption, electronic and toxic waste, and greenhouse gas emissions.
• Land use and infrastructure restrictions. Land use restrictions—such as zoning laws, environmental regulations, and infrastructure limitations—can significantly affect data center development. Ambiguous zoning codes may delay projects and create constraints, while environmental reviews of energy, emissions, and water use can add permitting and compliance costs. Limited power grid capacity can also make data center sites unsuitable, requiring additional capital for upgrades.
• Community pushback. Since 2023, over $60 billion worth of data center projects were blocked or delayed due to opposition from residents and activist groups. Virginia is currently the focal point for community opposition, with activist groups campaigning to slow, stop or further regulate data center development. Other states that rank among the top in opposition or are calling for increased regulation to data center development include Oregon, California, Arizona, Texas, Missouri and Indiana.
Conclusion
The need for data storage solutions will only continue to grow as technology drives innovation, turning data centers into an increasingly coveted CRE asset class.
As with any CRE transaction, it is vital for developers and investors to perform due diligence before committing to any project. Meticulously assessing the unique variables associated with data centers can help developers and investors make informed decisions about their investment. It is also essential to retain the services of a reputable title insurance company to confirm property ownership, identify potential liens and protect property owners from unforeseen title concerns.
At Old Republic Title, we understand what it takes to navigate complex CRE transactions. Our National Commercial Services Team has extensive experience supporting data center development across the nation and is ready to assist developers and investors with all their title and closing needs. To learn more about Old Republic Title’s title insurance products and closing services, or to connect with a knowledgeable team near you, visit oldrepublictitle.com/commercial/ncs.
Old Republic Title, its officers and employees do not provide, and this communication is not intended to be, investment, tax or legal advice. Old Republic Title makes no representations or warranties regarding the accuracy of the information or tax consequences addressed herein. You should consult an investment, tax or legal professional of your choosing to advise you of the benefits and risks of your specific transaction.